General information only, not personalized financial advice. Disclaimer.
January is the month when December’s spending arrives on your statements — and also the month most people are ready to make a change. This January budget reset takes about an hour and sets up the whole year.
No apps or spreadsheets needed. A piece of paper works.
Step 1: Face the holiday number
Add up what the holidays actually cost: gifts, food, travel, decorations, and anything still sitting on a credit card. Don’t judge it — just write it down. This number becomes next year’s holiday sinking fund goal (divide by 11 and you know what to save each month starting in February).
Step 2: Write down your take-home pay
Use what actually lands in your account each month, after taxes. If your income changes, use your lowest normal month.
Step 3: List your fixed bills
Rent or mortgage, utilities, phone, internet, insurance, car payment, minimum debt payments, childcare, subscriptions. While you’re here, run the subscription audit checklist and check if you’re overpaying for your phone plan.
Step 4: Set your flexible spending
Groceries, fuel, household items, personal care, kids, fun money. Look at last month’s statement for real numbers, not hopeful ones. If you overspend in the same categories every month, try cash stuffing for those.
Step 5: Plan for this year’s irregular costs
Look at the calendar for 2027 and list what you know is coming:
- Car registration, servicing and tires
- Birthdays, weddings, Mother’s and Father’s Day
- Back to school
- Annual subscriptions and insurance
- Holidays and travel
- Next Christmas
Each one gets a small monthly amount — that’s your sinking funds.
Step 6: Give every leftover dollar a job
Take-home pay − fixed bills − flexible spending − sinking funds = what’s left. Split it between:
- A starter emergency fund (aim for $500, then $1,000)
- Paying down holiday or high-interest debt
- One savings challenge for the year
If the number is negative, that’s important information too. Look for leaks first: the small-spend leak calculator and cheap grocery swaps are good places to start.
Step 7: Pick ONE savings goal for 2027
Just one. Write it at the top of a savings goal thermometer and stick it on the fridge. Some ideas:
- $1,378: the 52 week savings challenge 2027
- $5,050: the 100 envelope challenge
- $5,000: the $5,000 savings challenge
Bonus: a no-spend month to kick it off
Want quick momentum? Combine your reset with a no spend January. The money you don’t spend in January can fund your emergency fund or the first months of your challenge.
Check in monthly
Put a 15-minute money date in your calendar for the first Sunday of each month: compare what you planned with what happened, adjust, and shade your progress. Budgets work when they’re updated, not when they’re perfect.
General information only, not financial advice. For help with debt, free services exist — in the US, nonprofit credit counselors; in Australia, the National Debt Helpline (1800 007 007).
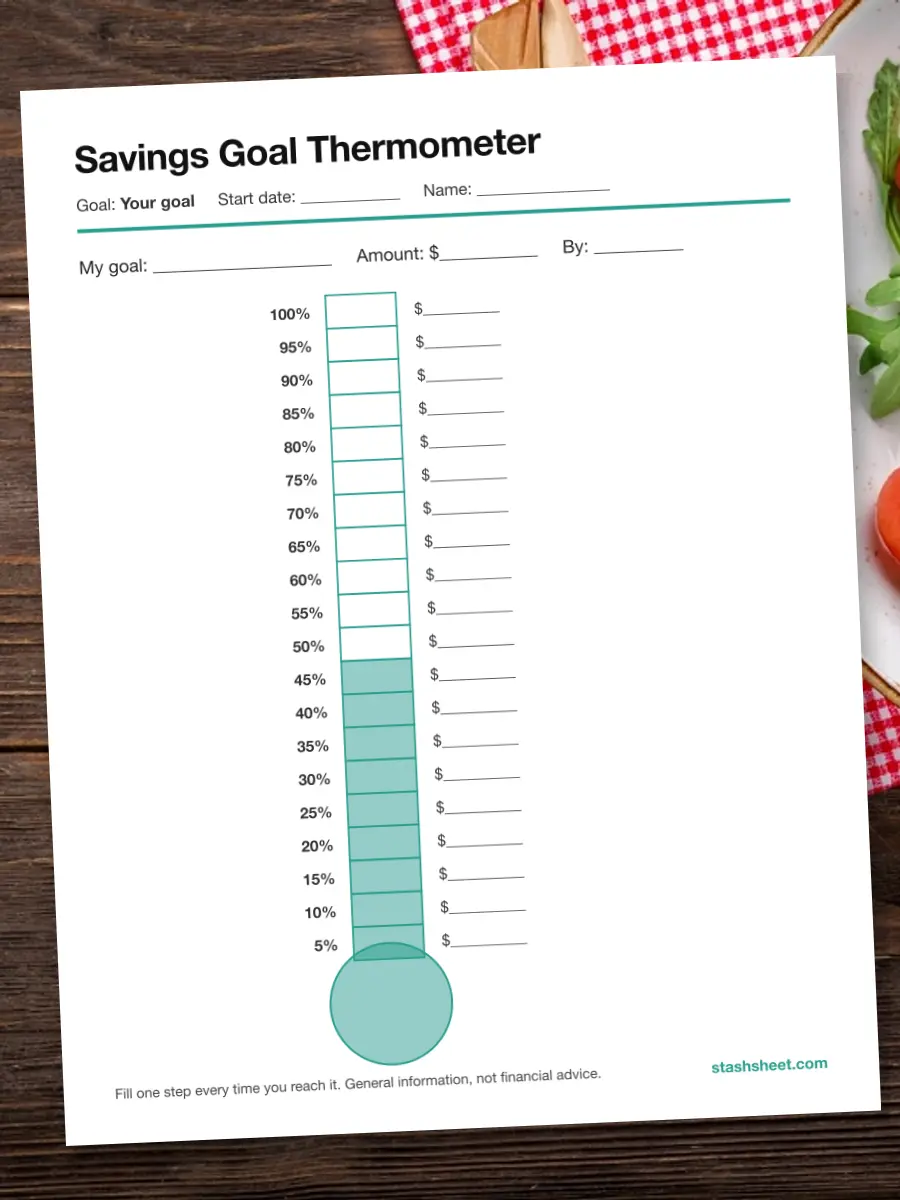
Savings Goal Thermometer
Write your goal at the top, split it into 20 steps and fill the thermometer as you go. Works for any amount. Free one-page PDF, no email needed.
Download free PDF PreviewFrequently asked questions
How do I make a budget for January?
Start with your take-home pay, subtract fixed bills, set amounts for groceries and fuel, include holiday bills that arrive in January, and give any money left a job: savings, debt or a sinking fund.
Why is January so hard financially?
Holiday spending shows up on January statements, some annual bills renew, and for many people it's a long month between paydays. Planning for it ahead makes it easier.
Sources
- CFPB: Your Money, Your Goals toolkit (budget, bill calendar and spending worksheets)
- CFPB: An essential guide to building an emergency fund
- NFCC: free resources from nonprofit credit counselors
- National Debt Helpline (Australia): help with debt problems
These are official, free resources. This article is general information, not personalized financial advice — for decisions about your own money, talk to a licensed professional or a nonprofit counselor.